How SWP calculators compute monthly cash flows from investments is a month-by-month loop: grow the balance by one month’s assumed return, subtract the withdrawal, and repeat until the money runs out or the tenure ends. The loop is simple. The assumptions hidden inside it decide whether the answer is realistic.
The Loop Inside the Calculator
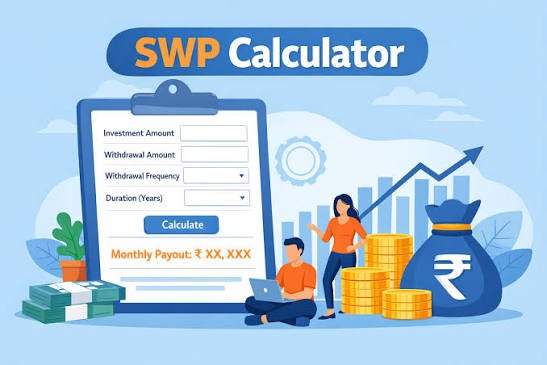
A systematic withdrawal plan sells mutual fund units on a schedule, and the calculator models the leftover pot.
- You enter the corpus, the monthly withdrawal, the expected annual return and the tenure
- Each month the remaining balance earns the monthly rate, then the withdrawal comes out
- One simulator writes it as Balance(m) = Balance(m−1) × (1 + r) − W, where r is the monthly rate and W the withdrawal
- Some sites print a closed formula such as A = P × [(1 + r)^n − (1 + r)^t] ÷ r, and others say there’s no single closed form, so they simulate
- Behind the scenes, the calculator also works out how many units to sell each month at the assumed NAV
Two Months by Hand
Take ₹50 lakh at an 8% annual return with ₹40,000 withdrawn monthly.
- The monthly rate is 8% ÷ 12, about 0.6667%
- Month 1: ₹50,00,000 grows to about ₹50,33,333, and after the ₹40,000 withdrawal you have ₹49,93,333
- Month 2: that grows to about ₹50,26,622, and after the next withdrawal you have ₹49,86,622
- The pot is shrinking slowly because ₹40,000 a month is more than the ₹33,333 the corpus earns at that rate
How Long the Money Lasts
When the balance runs down, the calculator solves for the number of months.
- The standard answer is n = −ln(1 − P × r ÷ W) ÷ ln(1 + r), my own derivation of the same loop
- For the example above, the corpus lasts about 270 months, or roughly 22.5 years
- Withdrawing ₹40,000 a month is ₹4.8 lakh a year, 9.6% of the corpus, which is why it depletes at an 8% return
- If you withdrew only ₹33,333 a month, the corpus would hold steady at this assumed return
The Quiet Conventions
Two settings you never see can shift the answer by years.
- Timing: one calculator assumes withdrawals at the end of each month, while another describes withdrawals from the first month, so the money leaves earlier. Starting the withdrawal at the beginning of each month shortens the example to about 22.1 years, my calculation
- Rate conversion: HDFC’s and another simulator divide the annual rate by 12, while a third converts using (1 + annual) ^ (1/12) − 1
- Dividing 8% by 12 is equivalent to an effective annual rate of about 8.3%. Using the true monthly equivalent of 8%, the same example lasts about 21.2 years
- So typing “8%” into two calculators can differ by over a year
Step-Up and Inflation Settings
Some calculators let withdrawals grow each year.
- A step-up raises the withdrawal by a fixed percentage every year, with one calculator’s 6% step-up meaning the amount grows 6% a year
- Inflation-adjusted versions work either by stepping up the withdrawal or by using real return, meaning return minus inflation, as the rate
- Either way, rising withdrawals shorten the life of the corpus, sometimes sharply
- Use your own inflation assumption, since defaults vary
What Calculators Ignore
The output is only as good as its constant-return assumption.
- Real returns vary, and a bad run early in withdrawals does more damage than the same average spread evenly, a sequence risk that a flat-rate model can’t show
- Many calculators apply no tax, no exit load and no fund expenses
- They ignore the NAV movements that decide how many units each withdrawal sells
- Many retirement planners use a 4% withdrawal rule as a starting point, adjusted for return and inflation expectations
How SWP Is Taxed
Tax doesn’t hit the whole withdrawal.
- Every SWP withdrawal is a redemption of units, and only the gain portion is taxable
- Units are redeemed first-in, first-out, so the earliest units go first
- If your units cost ₹100 and now trade at ₹150, a ₹40,000 withdrawal contains about ₹13,333 of gain and ₹26,667 of cost
- For equity-oriented funds, gains on units held 12 months or less are taxed at 20%, and long-term gains above ₹1.25 lakh a year at 12.5%
- Debt fund units bought on or after 1 April 2023 are taxed at your slab rate
Using One Sensibly
A few habits make the result more useful.
- Run it three times: your expected return, 2 points lower and 2 points higher
- Check the withdrawal rate, because a rate above the assumed return depletes the corpus
- Test a step-up to see the effect of inflation
- Read the fine print on whether withdrawals fall at the start or end of the month, and whether the rate is nominal or effective
FAQs
Q1. How do SWP calculators work?
They grow your balance by one month’s assumed return, subtract the withdrawal, and repeat for the chosen period.
Q2. Do SWP calculators include tax?
Many don’t, even though each withdrawal is a redemption with a capital gains portion that’s taxed.
Q3. Why do two calculators give different answers?
They may divide the rate by 12 or convert it to a true monthly rate, and withdraw at the start or end of the month.